Farm Equipment Finance WA
Helping WA farmers fund the machinery they need
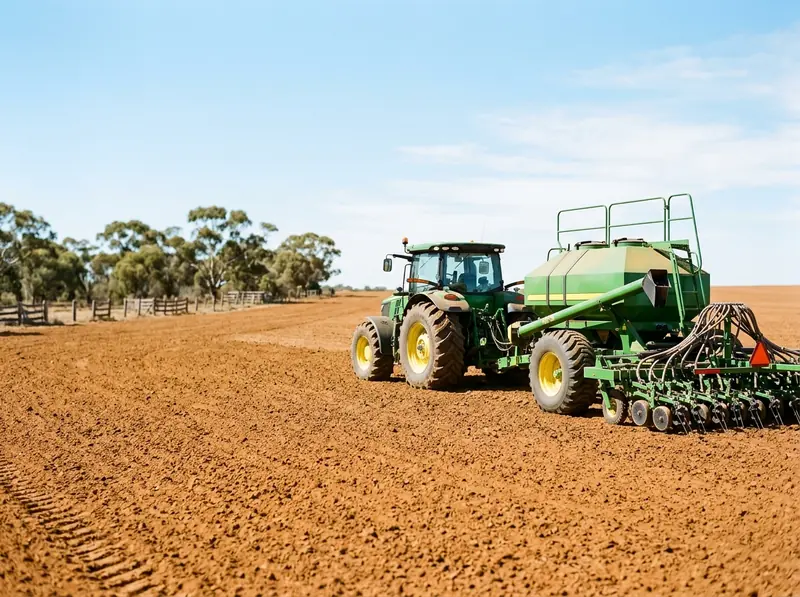
Running a farm in Western Australia means you rely on your machinery to get the job done. Whether you are seeding, harvesting, spraying, or irrigating, the right equipment keeps your operation moving. At Olsen Finance Group, we help clients across Perth and WA access farm equipment finance that suits the way their business actually works.
Why Farm Equipment Finance Matters
Farm machinery is one of the biggest capital investments a farming operation will make. Tractors, harvesters, air seeders, sprayers, and irrigation systems all carry significant price tags, and paying for them outright is not always the most practical option. Farm equipment loans allow you to spread the cost of essential machinery over time, keeping your cash flow intact so you can manage other costs across the season. Olsen Finance Group works with a wide panel of lenders to find finance structures that reflect the realities of farming, not just a standard commercial loan.
Finance Options for Farm Machinery
There is no single finance product that suits every farming operation. Olsen Finance Group helps clients across WA assess the options available to them, including chattel mortgage for farm equipment, farm equipment lease arrangements, and hire purchase for farm machinery. Each of these structures has different implications for ownership, tax treatment, and cash flow, so it is worth understanding what each one means for your specific situation before committing.
A chattel mortgage for farm equipment is one of the most commonly used structures in agribusiness. You take ownership of the asset from day one, and the lender holds a mortgage over it as security. This can allow eligible businesses to claim GST on the purchase price upfront, which is a meaningful benefit for registered operations. A farm equipment lease, on the other hand, means the lender retains ownership of the asset during the term, and you make regular payments to use it. Hire purchase for farm machinery sits somewhere in between, with ownership transferring to you once all repayments are made.
Flexible Repayment Structures for Seasonal Businesses
One of the most important things Olsen Finance Group looks for when arranging farm equipment finance is a repayment structure that reflects the seasonal nature of farming income. Seasonal repayment farm finance and harvest repayment structures allow you to align your repayments with the times of year when income is strongest. Rather than making fixed monthly payments regardless of cash flow, you can structure repayments around your harvest cycle or income periods. This is particularly relevant for broadacre farm equipment loans, where the scale of the operation and the timing of income can vary significantly from year to year.
Finance for All Types of Farm Equipment
Olsen Finance Group assists clients with finance across a wide range of machinery and equipment types. This includes tractor finance for farms, harvester finance, air seeder finance, sprayer finance, and irrigation equipment finance. We also assist with contract harvester finance for operators who run harvesting services across multiple properties, as well as agribusiness equipment loans for larger or more complex operations.
If you are purchasing through a private sale, farm machinery private sale finance is also available. Private sales are common in the agricultural sector, and Olsen Finance Group has experience working with lenders who are comfortable with this type of transaction.
Low Doc and New ABN Options
Not every farming business has two years of full financials ready to go. If you are a newer operation or have recently restructured, low doc farm equipment finance and farm equipment finance for new ABN holders may be available through certain lenders on our panel. These options are assessed differently to standard applications, and Olsen Finance Group can help you understand what documentation may be required and which lenders are likely to consider your circumstances.
Working with Olsen Finance Group
Olsen Finance Group works with clients across Perth and regional WA to arrange farm finance that fits the scale and structure of their operation. We take the time to understand your business before recommending a finance structure, and we work across a broad panel of lenders to find options suited to your needs. Whether you are looking at equipment finance for the first time or refinancing existing machinery debt, our team is here to help you find a practical path forward.
If you are also considering broader business funding, our team can also discuss business loans and asset finance options that may complement your farm equipment finance arrangements. We work with clients at every stage of their farming operation, from new entrants to established broadacre producers across Western Australia.
Step 1: Initial Conversation
Everything starts with a chat. We take the time to understand your situation, your goals, and what you are trying to achieve. Whether you are a self-employed business owner or a PAYG professional, we listen first and talk numbers second.
Step 2: Fact Find and Assessment
Once we understand your goals, we dig into the details. We look at your income, assets, liabilities, and credit position to get a clear picture of where you stand and what is possible.
Step 3: Strategy and Structuring
This is where our expertise comes in. We identify the right loan structure for your circumstances and map out a strategy that suits your short and long-term financial goals.
Step 4: Lender Research and Comparison
We search across a wide panel of lenders to find the most suitable options for you. We compare rates, fees, features, and lending policies so you do not have to.
Step 5: Recommendation and Approval in Principle
We present you with a clear recommendation and walk you through your options. Once you are happy, we work to secure an approval in principle so you can move forward with confidence.
Step 6: Application and Submission
We handle the paperwork. Our team prepares and submits your application, manages the lender communication, and keeps things moving so there are no unnecessary delays.
Step 7: Settlement and Beyond
Once your loan settles, our job is not done. We stay in touch to make sure your finance continues to work for you. As your situation changes, we are here to review and adjust your strategy along the way.
Caroline has been amazing to deal with during this process of refinancing my home loan. She investigated options for me and listened to what I wanted out of my home loan. She’s always been one step ahead and informed me of the next steps from start to finish. Thank you for making this process so easy. Highly recommend!
Tanya Spencer
We had such a great experience with Caroline Hodgson at Olsen Finance! She was amazing throughout the whole process of getting our home loan sorted. Caroline took the time to compare different lenders and interest rates to make sure we were getting the best deal possible. She was always happy to answer our questions, kept us updated along the way and made the whole process so much easier and less stressful. We're so grateful for all her help and would definitely recommend Caroline to anyone looking for a mortgage broker. Thanks so much, Caz and Olsen Finance!!
josh taylor
Caroline at Olsen was so easy to deal with! We where given a few options and walked through what best suited our situation. Caroline was amazing with answering financial questions I had no idea about and nothing was a bother even when we changed our plans midway through the application process! Highly recommend and wouldn’t hesitate to use Olsen financial group in the future if needed
Jessica Vanderwey
We recently worked with Caroline for our home loan application, and we couldn’t be happier with the outcome. She was incredibly professional, knowledgeable, and guided us through the complexities of our DHOAS entitlements with ease. Caroline’s communication was excellent, always keeping us informed and working hard to secure our approval in time. Highly recommend her services to anyone looking for a dedicated and expert broker.
Liam
I cant recommend Amy at Olsen Finance highly enough! Amy made the whole process so easy and stress-free from start to finish. She was incredibly knowledgeable, patient and always happy to answer our questions and explain everything clearly. We really appreciated how much effort Amy put into finding the right option for us and making sure we understood everything along the way. Nothing ever felt like too much trouble, and we always felt like she genuinely had our best interests at heart. If you’re looking for a broker who is professional, reliable, approachable and genuinely goes above and beyond for her clients, we wouldn’t hesitate to recommend Amy..
Tamara RORBACH
Frequently Asked Questions
A mortgage broker acts as the link between you and a wide range of lenders, including banks, credit unions, and non-bank lenders. Rather than going directly to a single lender and being limited to their products, a broker assesses your financial situation and searches across multiple options to find lending solutions that suit your needs and goals. At Olsen Finance Group, we handle the research, paperwork, and communication with lenders on your behalf. This saves you considerable time and effort, and means you have a knowledgeable professional in your corner throughout the entire process, from your initial enquiry right through to settlement.
We assist clients across a wide range of finance needs, including:
- Home loans for owner-occupiers and first home buyers
- Investment property loans
- Refinancing existing loans
- Commercial property finance
- Business lending
- Equipment finance
- Vehicle finance
We work with a wide panel of lenders, so we can explore a range of products to find the right fit for your situation.
A fixed rate home loan locks in your interest rate for a set period, which means your repayments stay the same during that time regardless of changes in the broader market. This can provide certainty around your budget and cash flow. A variable rate loan, on the other hand, has an interest rate that can move up or down in line with lender decisions and market conditions. Variable loans often come with more flexibility, such as the ability to make additional repayments or access a redraw facility. Some borrowers also choose a split loan, which combines both fixed and variable portions. At Olsen Finance Group, we help you understand the implications of each option so you can make an informed decision that aligns with your circumstances and goals.
When you go directly to a bank, you are only seeing what that one institution can offer. A mortgage broker like Olsen Finance Group has access to a panel of lenders, which means we can compare a much wider range of options on your behalf. This is particularly valuable if your situation is not straightforward, such as being self-employed, having variable income, or looking for a loan structure that suits a specific purpose. Beyond access to lenders, we also bring expertise, experience, and genuine support throughout the process. We take the time to understand your goals, explain your options clearly, and advocate for you with lenders. Our focus is on building long-term relationships with our clients, not just completing a single transaction.
LMI stands for Lenders Mortgage Insurance. It is a one-off insurance premium that protects the lender, not the borrower, in the event that a loan cannot be repaid. LMI is typically charged when a borrower has a deposit of less than 20 per cent of the property's purchase price. The cost of LMI varies depending on the loan amount and the size of your deposit. In some cases it can be added to the loan balance rather than paid upfront. At Olsen Finance Group, we can help you understand whether LMI applies to your situation and explore options that may allow you to avoid or reduce it.
Yes, self-employed business owners can apply for home loans and other finance products in Australia. However, the application process can be more involved than it is for someone who receives a regular salary. Lenders typically want to see evidence of your income over time, which may include tax returns, business financial statements, and notices of assessment from the Australian Taxation Office. Some lenders also offer low-doc loan options for those who may not have the full suite of standard documentation. At Olsen Finance Group, we work with self-employed clients regularly and understand the unique challenges involved. We help you prepare your application in a way that presents your financial position clearly and accurately to lenders.
Yes. Lenders in Australia require a deposit as part of a home loan application. The size of the deposit required can vary depending on the lender, the type of property, and your overall financial profile. A deposit of at least 20 per cent of the property's purchase price is generally preferred by lenders as it avoids the need for Lenders Mortgage Insurance (LMI). Some lenders do consider applications with a smaller deposit, and there are also specific schemes and packages that may change what is required. First home buyers may have access to low deposit government schemes that allow eligible applicants to purchase with as little as 5 per cent deposit. Medico and professional packages offered by certain lenders can also come with different deposit requirements, meaning eligible borrowers may be able to borrow with a reduced or waived LMI requirement. At Olsen Finance Group, we help you understand what is required for your situation and how to position your application accordingly.
Mortgage brokers in Australia are paid a commission by the lender once your loan settles. This means you do not pay us directly for our broking services. We are required by law to disclose all commissions and fees upfront, so you will always know exactly how we are compensated before you proceed. Our obligation is to act in your best interests, not the lender's. This is a legal requirement under the best interests duty that applies to all licensed mortgage brokers in Australia. We are transparent about how we are paid and are always happy to walk you through the details during your consultation.
Refinancing means replacing your existing loan with a new one, either with your current lender or a different one. People refinance for a variety of reasons, including accessing equity in their property, consolidating debts, changing loan features, or simply reviewing whether their current loan still suits their circumstances. It is worth noting that refinancing is not always the right move for everyone, and there can be costs involved such as discharge fees, application fees, and other charges depending on your current loan and the new product. At Olsen Finance Group, we take the time to review your current situation thoroughly before making any recommendations. We want to make sure any change you make genuinely serves your financial goals.
The documents required will depend on your employment situation and the type of loan you are applying for. For PAYG employees, lenders typically require recent payslips, bank statements, identification documents, and details of any existing debts or liabilities. For self-employed applicants, you will generally need to provide personal and business tax returns, financial statements, and ATO notices of assessment, usually for the past two years. You may also need to provide details of any assets you own. At Olsen Finance Group, we provide you with a clear checklist of what is needed before you begin, so you can gather everything in an organised way and avoid unnecessary delays in your application.
The timeline for a home loan application can vary depending on a number of factors, including the complexity of your financial situation, the lender you apply with, and how quickly documentation is provided. In general, once a full application is submitted with all required documents, lenders may take anywhere from a few business days to a few weeks to issue a formal approval. At Olsen Finance Group, we work to keep the process moving efficiently by helping you prepare a thorough and accurate application from the outset. We stay in regular contact with lenders on your behalf and keep you updated throughout the process so you always know where things stand.
Olsen Finance Group Pty Ltd ABN: 23 697 562 646. Credit Representatives #543071 and #556392 are authorised under Australian Credit Licence #389087.
Testimonials are provided by clients of Olsen Finance. Results and experiences may vary. Testimonials do not constitute financial or credit advice.
Disclaimer: This page provides general information only and has been prepared without taking into account your objectives, financial situation or needs. We recommend that you consider whether it is appropriate for your circumstances and your full financial situation will need to be reviewed prior to acceptance of any offer or product. It does not constitute legal, tax or financial advice and you should always seek professional advice in relation to your individual circumstances.
Site by Broker Studio